Antonio Caputo
This indicator examines gross electricity generation in Italy, broken down by source, from 1990 to 2024. Total generation rose from 216.6 TWh in 1990 to a peak of 314.1 TWh in 2007, before settling at 271 TWh in 2024. The energy mix has undergone a profound structural transformation: whilst traditional thermal power remains the leading source at 152.1 TWh in 2024 (56.1 per cent of the total), its share has declined compared with the past. At the same time, the combined output from wind and solar power rose from just 6 GWh in 1990 to 58.3 TWh in 2024 (21.5 per cent of the total), alongside hydroelectric generation (54.8 TWh), geothermal generation (5.7 TWh) and bioenergy (17.2 TWh) . The contribution of all renewable sources (hydroelectric, geothermal, wind, solar photovoltaic and bioenergy), excluding production from pumped storage, was approximately 50 per cent
The indicator measures the electricity generated by each of the primary energy sources.
To assess the contribution of different energy sources to electricity generation, with a view to increasing the use of less polluting fuels.
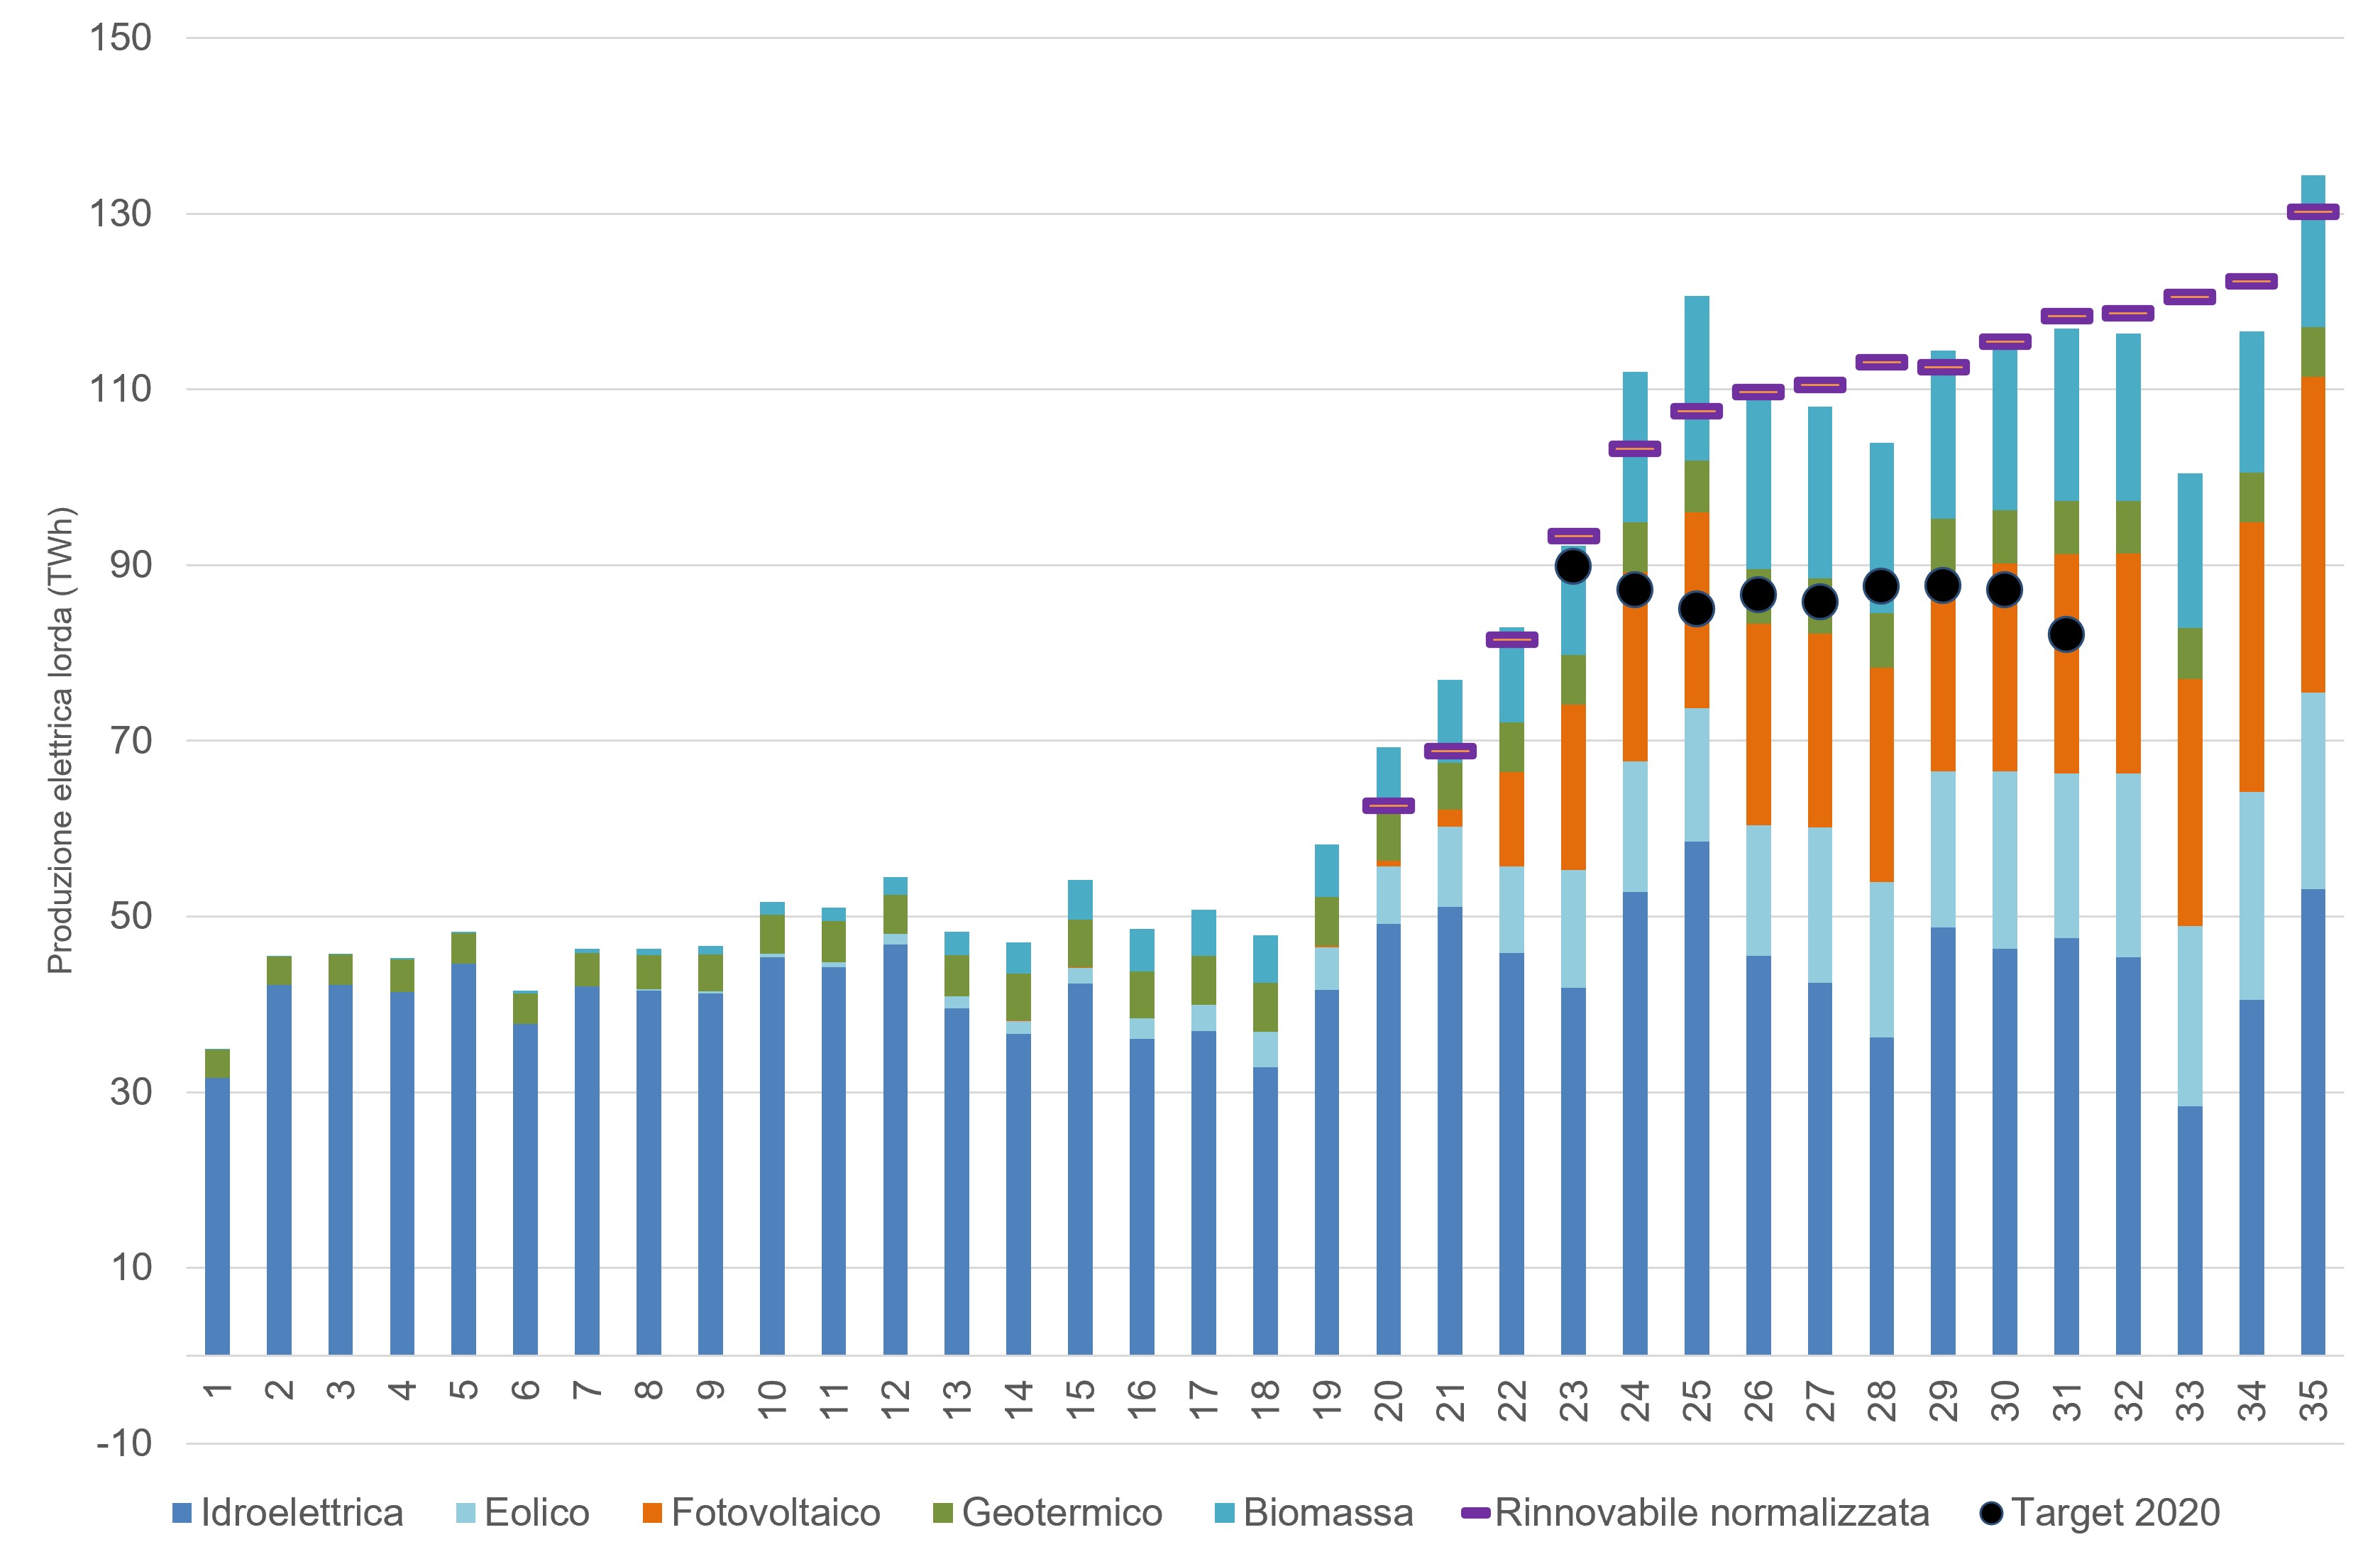
The indicator has no specific reference to targets set by legislation. Regulatory developments in the Italian electricity sector reflect the gradual transition from a centralised, fossil-fuel-based model to a sustainable, efficient generation system driven by renewable sources. The first key milestone in this process was Legislative Decree 79/1999, known as the Bersani Decree, which initiated the liberalisation of the electricity market and promoted the gradual phasing out of fuels with a high environmental impact, such as fuel oil, in favour of natural gas. Subsequently, to encourage the uptake of clean technologies, the ‘Conto Energia’ Decrees were introduced between 2005 and 2013, supplemented by the auction and registry mechanisms provided for in Ministerial Decree 28/2011 and Ministerial Decree FER 1; this comprehensive framework of incentives led to an increase in photovoltaic and wind power generation, particularly between 2008 and 2015. In particular, Directive 2009/28/EC, transposed into national law by Legislative Decree No. 28 of 3 March 2011, sets out the targets for energy from renewable sources as a proportion of gross final consumption by 2020 for each European Union country; these targets include both energy consumption from renewable sources for electricity generation and that for heating and transport. The indicative target for the electricity sector by 2020, calculated as the ratio of normalised electricity generation from renewable sources to gross domestic consumption, stood at 26.4 per cent, whilst the indicative target set by the PNIEC for 2030 is 63 per cent. Legislative Decree No. 199 of 2021, which implements Directive (EU) 2018/2001 on the promotion of renewable energy, sets out the allocation among regions and autonomous provinces of the minimum capacity of renewable energy plants. Following the aforementioned legislative decree, the decree of the Ministry of the Environment and Energy Security (MASE) of 21 June 2024, sets out the allocation amongst regions and autonomous provinces of the national target for 2030 of 80 GW of additional capacity from renewable sources compared with 31 December 2020, necessary to achieve the targets set by the National Energy and Climate Plan (PNIEC) and to meet the new targets arising from the implementation of ‘Fit for 55’, also in light of ‘Repower EU’. The monitoring and verification of compliance with the requirements set out in the Decree of 21 June 2024 are the responsibility of MASE, with the support of GSE and RSE.
Terna - Rete Elettrica Nazionale S. p. A.
TERNA S. p. A, Dati statistici sull'energia elettrica in Italia https://www. terna. it/it/sistema-elettrico/statistiche/pubblicazioni-statistiche
National
1990-2024
The data is available at national and regional level, with a more aggregated classification of renewable energy sources (hydropower, thermoelectric, renewable). Since 2000, GRTN (later Terna Rete Italia SpA) has published data on the consumption of fuels used in conventional thermoelectric power generation only in aggregated form, by fuel class.
In 2024, the Italian electricity generation system is at an advanced stage of the energy transition, with renewable sources (hydroelectric power, excluding the contribution from pumped storage and stand-alone storage, wind, solar photovoltaic, geothermal and biomass) accounting for 49.5 per cent of gross national generation. Natural gas remains the main driver of the transition and of system reliability, generating 118.6 TWh (43.7 per cent of the total). Of particular note is the now almost definitive decline in solid fuels (coal), which have fallen to just 3.9 TWh (1.5 per cent of the total), and in petroleum products (8.6 TWh). Furthermore, the item relating to stand-alone storage systems begins to appear in the balance sheet (136 GWh in 2024), signalling the start of the roll-out of large-scale storage systems (Table 1).
In 2024, total electricity generation stood at 271 TWh (+20.1 per cent compared with 1990), representing a 2.3 per cent increase on the previous year (Table 1). The decline in 2020 was due to the lockdown measures imposed on economic activities that had to be adopted to contain the spread of the SARS-CoV-2 pandemic, measures which reduced demand for electricity. In 2021, there was a recovery in electricity generation, followed by a further decline over the last two years. Of particular note is the growth in the contribution of renewable sources between 2007 and 2014, from 15.5 per cent to 43.4 per cent, with a consequent decrease in the share of natural gas (from 55 per cent to 33.5 per cent). The trend over the past thirty years reveals a two-stage technological shift. The first phase, spanning the late 1990s and early 2000s, saw natural gas replace petroleum products (which fell from 102.7 TWh in 1990, accounting for 47.4 per cent of the mix, to less than 9 TWh in 2024). The second phase, which began around 2008–2010, involved the exponential growth of non-dispatchable renewables: wind and solar power increased tenfold over fifteen years, rising from 4.1 TWh in 2007 to over 58 TWh in 2024. At the same time, hydropower has maintained its role as a pillar of the renewable energy mix, whilst being affected by climatic variability (with a low of 30.3 TWh in 2022 and a recovery to 54.8 TWh in 2024). The overall trend points to a gradual decarbonisation of national electricity generation, accompanied by a sharp decline in coal use over the last three years (from 22.6 TWh in 2022 to less than 4 TWh in 2024) (Figure 1).
In recent years, the thermoelectric sector has seen a reduction in the share of natural gas, whilst the share of renewable energy, following the decline recorded in 2022, has exceeded the peak level of 2014. The sharp reduction in the share of renewable energy in 2022 (35.6 per cent) was caused by the decline in hydroelectric generation. Energy from wind and solar power rose from 1 per cent in 2007 to 22 per cent in 2024. Following a rapid increase in electricity generated from these sources between 2007 and 2014, there was a slowdown in the previously observed rates of electricity generation up to 2020, followed by significant annual increases up to 2024. The contribution of the thermal power sector (56 per cent in 2024) shows a significant decrease over the last year. In 2014, the lowest figure (63 per cent) was recorded, prior to that recorded in 2024.
| Data |
|---|
Headline
Table 1: Gross electricity generation by source Data source
Terna |
Thumbnail
Headline
Figure 1: Gross electricity generation by source. Data source
Terna |
The historical data reflects the effectiveness of the decarbonisation policies implemented in the Italian electricity sector. The drastic reduction in the use of coal and oil, first in favour of natural gas and subsequently of renewable sources, has led to a significant reduction in specific emissions per kWh generated. However, the fact that over 56 per cent of generation comes from thermal power highlights that the system still requires a massive acceleration in the installation of renewable energy capacity (particularly solar and wind power) and in the development of the electricity transmission grid and storage systems. The challenge in the coming years will be to replace the remaining share of natural gas through the further installation of renewable energy plants and the integration of large-scale storage systems, whilst ensuring the stability and security of the national electricity grid.